
Variance and Standard Deviation Cheat Sheet
31 Oct 2026
Quick answer
A quick revision cheat sheet on variance and standard deviation for SSC, Banking, Railway and state exams. It covers the mean, the variance formula and its shortcut form, the standard deviation, what the two measures tell you about spread, and the effect of adding or multiplying the data, with worked examples to revise quickly.
Variance and Standard Deviation Cheat Sheet
Quick Revision
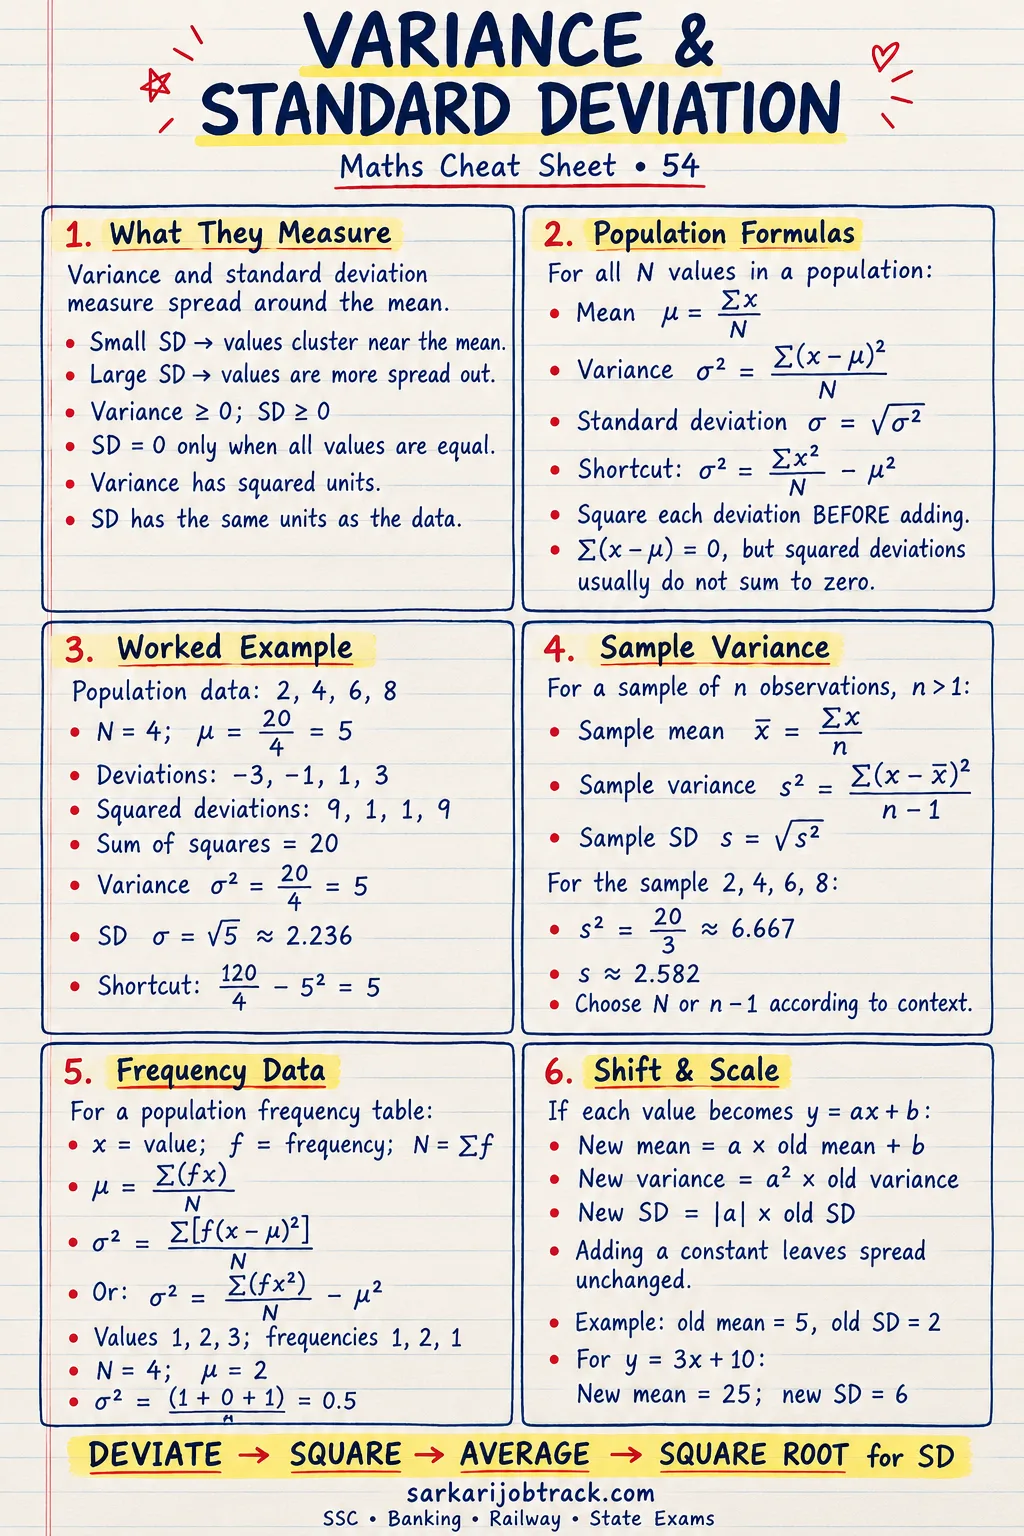
Variance and standard deviation both measure how far a set of values spreads out from its mean. The standard deviation is simply the square root of the variance, so it is in the same units as the data.
1. The Mean
Mean (x̄) = Σx / nEvery measure of spread is taken about this mean.
2. Variance
Variance (σ²) = Σ(x − x̄)² / nShortcut form, which avoids the deviations:
σ² = (Σx² / n) − x̄²3. Standard Deviation
Standard deviation (σ) = √(variance)A small σ means the values cluster near the mean; a large σ means they are widely scattered.
4. Effect of Changing the Data
- Add a constant
kto every value → the mean rises byk, butσis unchanged. - Multiply every value by
k→ the mean andσare both multiplied by|k|, and the variance byk².
5. Worked Example
For the data 2, 4, 6, 8:
Mean      = (2 + 4 + 6 + 8) / 4 = 5
Deviations = −3, −1, 1, 3  →  squares 9, 1, 1, 9  →  sum 20
Variance  = 20 / 4 = 5
SD        = √5 ≈ 2.24
6. Exam Quick Tips
- Variance is never negative — it is an average of squares.
- The standard deviation carries the same unit as the data; the variance does not.
- Adding the same number to every value does not change the spread.
Keep revising with the rest of the Maths section:
How this was made: Drafted with AI assistance; spot-checked by the editor on 31 October 2026.